What Credit Score Do I Need to Buy a House? There Isn’t One Number
This is an important question, and it’s another one where if somebody gives you a hard number, they’re guessing at best.
There are no hard and fast rules anymore about the credit score you need to borrow money for a house. There are hundreds of loan programs out there. Some have a credit score requirement. Some don’t have one at all. Others look at your whole credit picture alongside your income, your debt-to-income ratio, and a handful of other things we live in every day and you’ve probably never had a reason to hear of.
So the real answer isn’t a number. It’s a picture.
Ask Mike’s AI — answers instantly, no forms
Better credit doesn’t just mean approved. It means choices.
This is the part I most want people to understand.
The better your credit, the more options you have. Not simply a yes instead of a no. More doors open, and you get to pick which one you walk through.
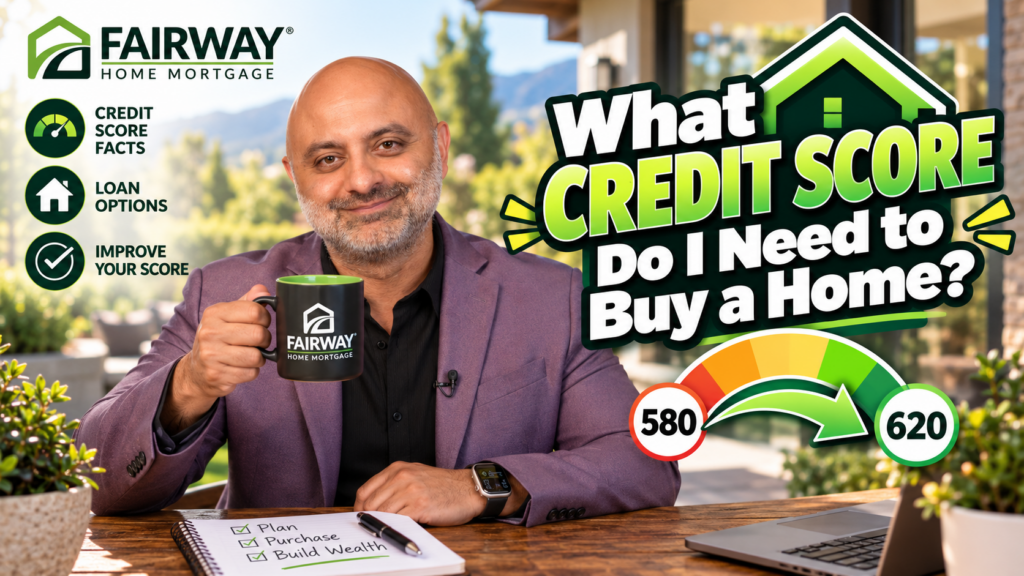
Say you’re sitting at 580. You might qualify perfectly well right there. But if we can help you get to 620, that could meaningfully lower what you pay every month for the exact same house. Same address, same price, same you, and a different cost, because the score moved.
Why one number moves so much
Credit scores do more than decide approval.
Depending on the program, your score can also affect the interest rate you’re offered. The rate drives your monthly payment. The payment drives how much house you can actually afford. So a score you thought was just a gate turns out to be sitting underneath the whole budget.
That’s why I don’t like answering this question with a number. The number on its own doesn’t tell you anything useful. It’s a puzzle, and the pieces only make sense together: score, income, debts, program, and what you’re trying to buy.
Putting that puzzle together with people is the job.
Wherever you are now is not where you have to stop
Here’s what we pride ourselves on.
If your score isn’t where you want it, that’s a starting point, not a verdict. We help people improve their credit every single day, and we turn “not yet” into “let’s go” all the time.
Sometimes it’s a small, specific fix that nobody told you about. Sometimes it’s a few months of doing a couple of things differently. Either way, you want to know that before you start looking at houses, not after an offer falls apart.
And it costs you nothing to find out where you stand.
You need more than a good rate
If you take one thing from this: don’t let a number you read online decide whether you call someone.
The score matters. What matters more is knowing what it’s actually doing to your options, and whether there’s a move worth making before you buy. That’s not a rate question. That’s a plan.
Common questions
What credit score do I need to buy a house?
There are no hard and fast rules anymore. Some loan programs have a credit score requirement, some have none at all, and others weigh your whole credit picture alongside your income and your debt to income ratio. The real answer is a picture rather than a number.
Does a better credit score do more than get me approved?
Yes, and this is the part worth understanding. The better your credit, the more options you have. Depending on the program your score can also affect the interest rate you are offered, which affects your monthly payment, which affects how much house you can afford.
Can a small increase in my score change what I pay?
It can. Say you are sitting at 580. You might qualify perfectly well there, but getting to 620 could meaningfully change what you pay every month for the exact same house. Same address, same price, different cost, because the score moved.
What if my credit score is not where I want it?
That is a starting point, not a verdict. We help people improve their credit every day and turn not yet into lets go all the time. You want to know where you stand before you start looking at houses rather than after an offer falls apart.
Everything above is general. Your credit report isn’t. Ask about your own situation: the old collection, the card you keep near its limit, whatever’s actually on your mind. It’s Mike’s AI, so it’s awake at 11pm, and it collects nothing.
Ask Mike’s AI
Ready for a person?
If you want to know what your credit is really doing to your options, that’s a short conversation and it costs you nothing.
- Book a time with my team: we’ll tell you straight what your credit picture opens and what it closes
- Start an application: if you already know you’re ready to move
- Or call the office on (314) 478-3699
This information is not intended to be an indication of loan qualification, loan approval or a commitment to lend. Other limitations may apply. This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates, and programs are subject to change without prior notice. All products are subject to credit and property approval. Not all products are available in all states or for all dollar amounts. Fairway is not affiliated with any government agencies.
Mike Swaleh, Area Manager, NMLS #739145. Fairway Independent Mortgage Corporation, NMLS Entity ID #2289. Equal Housing Opportunity.
Let's talk about your credit, not a number online
The article is the same for everyone. Your numbers aren’t. Ask about your own situation — whatever’s actually on your mind. It answers straight away.
You’re chatting with Mini Mike, an AI built on Mike’s own answers, not the real Mike. No forms and no contact details needed to ask.
 Buying a Home With Variable or Commission Income in Lincoln, CA: How Mortgage Approval Really Works (2026 Guide)
 Can You Buy a Home With a Reverse Mortgage? A 2026 Guide to HECM for Purchase in Lincoln, CA
 Buying a Home After Retirement in Lincoln, CA: Mortgage Options, Income Rules, and Downsizing Tips for 2026
Why people work with Mike
This information is not intended to be an indication of loan qualification, loan approval or a commitment to lend. Not all customers will qualify. Fairway is not affiliated with any government agencies. Mike Swaleh, Mortgage Advisor, NMLS #739145. Fairway Independent Mortgage Corporation, NMLS Entity ID #2289. Equal Housing Opportunity.