Prequalified vs Preapproved, and the Two Levels Above Both
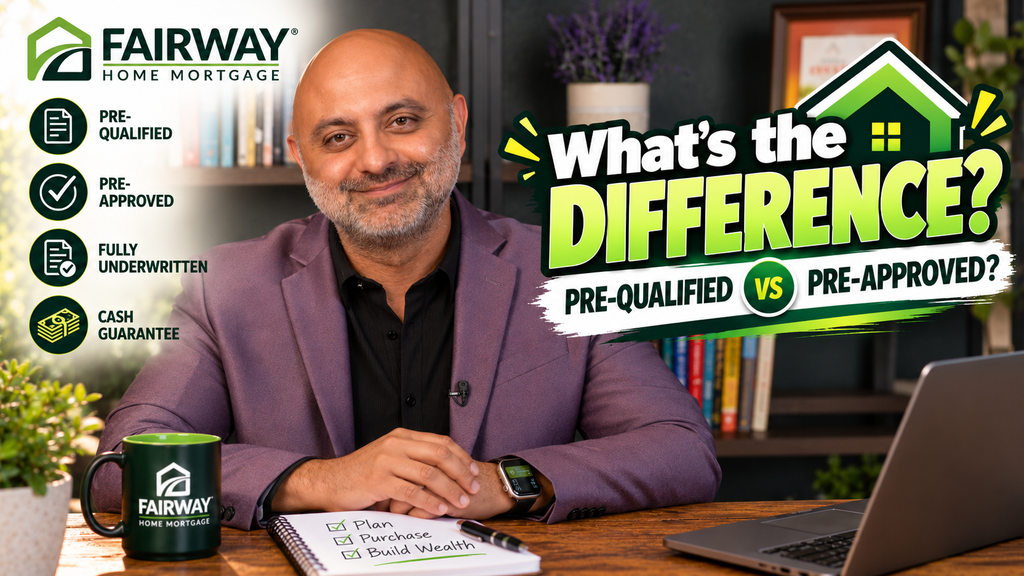
Everybody asks me the difference between prequalified and preapproved. It’s a fair question, and the answer matters more than most people expect. It can be the reason your offer gets taken seriously or set aside.
But what if I told you it’s more complicated than two options?
At Fairway we work in four levels. Knowing which one you’re holding is the difference between hoping your offer lands and knowing it will.
Ask Mike’s AI — answers instantly, no forms
Level one: prequalification
This is the lightest version.
Somebody pulls your credit, takes your word for your income and assets, and says, “you know what, this might work.” Then they hand you a prequalification letter.
Notice the word might. Nothing has been verified except your credit. If your income works differently than you described it, and income is more complicated than most people realize, the whole thing can come apart later.
We really don’t do much of that around here.
Level two: a true pre-approval
This is our minimum, and it’s a different animal.
A pre-approval goes past the credit check and your stated numbers. We actually verify your income and assets, using pay stubs, W-2s, or any of a number of other methods depending on how you’re paid, in addition to pulling your credit.
Two things come out of that. First, when I hand you your letter, you can carry it with confidence, because we’ve checked the things that would otherwise surprise you in week three. Second, that letter reads very differently to a seller and a listing agent than a prequalification does. They’ve seen both. They know the difference.
Level three: a fully underwritten pre-approval
Here’s where it gets interesting, and where most buyers have no idea the option exists.
At level three, your file goes through underwriting before you’ve found a house. That does three things for you.
It lets you shorten your window once you’re in escrow, and a shorter timeline is a real negotiating chip, sometimes worth more to a seller than money.
It can put you in a position to waive your financing contingency, which makes your offer considerably more competitive.
And it front-loads the work. By the time you find the house you actually want, there’s very little left for us to do, which is exactly when you don’t want to be hunting for documents.
Level four: our cash guarantee program
But wait, there’s more.
Level four is where we take Fairway’s cash and back your offer. We go beyond the initial underwrite and get your client conditions cleared, and then our backing goes on the contract for your home.
What that does is put you on a footing that, in some cases, is as good as cash.
That matters because competing against a cash offer as a financed buyer is genuinely hard. Sellers take the certain thing. This is how we make the certain thing be you. Terms and eligibility apply, and whether it fits is part of the conversation.
You need more than a good rate
Four levels, and the right one depends entirely on what you’re walking into.
In a quiet market with a motivated seller, level two may be all you need. In a market where you’re one of six offers, the difference between level two and level four is the difference between writing offers and owning a house.
That’s not something a rate sheet can tell you. That’s a plan, and picking the right level, early, is one of the highest-leverage decisions in the whole process.
Common questions
What is the difference between being prequalified and preapproved?
Prequalification looks at your credit and takes your word for your income and assets, then issues a letter saying this might work. A pre-approval verifies your income and assets with documents such as pay stubs and W-2s, so the letter reflects something that has actually been checked.
Why does a pre-approval letter help my offer?
Sellers and listing agents have seen both kinds of letter and they know the difference. A verified pre-approval reads very differently in front of them, and because the checks are already done there are fewer surprises later in the process.
What is a fully underwritten pre-approval?
Your file goes through underwriting before you have found a house. That lets you shorten your window once you are in escrow, which is a real negotiating chip, can put you in a position to waive your financing contingency, and front loads the paperwork so there is little left to do when you find the house you want.
What is the cash guarantee program?
It is the fourth level. Fairway backs your offer with its own cash once your client conditions are cleared, which puts our backing on the contract and in some cases puts you on a footing as good as cash. Terms and eligibility apply, so whether it fits is part of the conversation.
Which level is right depends on what you’re competing against, and that’s local. Ask about your own situation: the market you’re shopping, the offer you just lost, whatever’s actually on your mind. It’s Mike’s AI, so it’s awake at 11pm, and it collects nothing.
Ask Mike’s AI
Ready for a person?
If you’re about to start writing offers, this is the conversation to have first rather than third.
- Book a time with my team: we’ll work out which level fits what you’re up against
- Start an application: if you already know you’re ready to move
- Or call the office on (314) 478-3699
This information is not intended to be an indication of loan qualification, loan approval or a commitment to lend. Other limitations may apply. This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates, and programs are subject to change without prior notice. All products are subject to credit and property approval. Not all products are available in all states or for all dollar amounts. Fairway is not affiliated with any government agencies.
Mike Swaleh, Area Manager, NMLS #739145. Fairway Independent Mortgage Corporation, NMLS Entity ID #2289. Equal Housing Opportunity.
Not sure which level you need?
The article is the same for everyone. Your numbers aren’t. Ask about your own situation — whatever’s actually on your mind. It answers straight away.
You’re chatting with Mini Mike, an AI built on Mike’s own answers, not the real Mike. No forms and no contact details needed to ask.
Why people work with Mike
This information is not intended to be an indication of loan qualification, loan approval or a commitment to lend. Not all customers will qualify. Fairway is not affiliated with any government agencies. Mike Swaleh, Mortgage Advisor, NMLS #739145. Fairway Independent Mortgage Corporation, NMLS Entity ID #2289. Equal Housing Opportunity.